Flooded or fire damage right now? Call 24/7 — (239) 555-0199 for an emergency restoration company near you.
Insurance
Does Renters Insurance Cover Hurricane Damage? What You Need to Know
Practical, Florida-specific guidance from our restoration team.
SR
SWFL Restoration Editorial
Oct 21, 2026 6 min read
Key Takeaways
- Renters insurance covers personal belongings damaged by wind or rain entering through a storm-damaged roof.
- Standard policies explicitly exclude damage caused by rising water or storm surges.
- Flood insurance is a separate product, often backed by the National Flood Insurance Program.
- Additional living expenses may be covered if your rental unit is rendered uninhabitable by a covered peril.
- Hurricane deductibles are distinct from standard deductibles and are often calculated as a percentage of your total coverage limit.
- Renters should consider flood insurance to protect against rising water.
Does Renters Insurance Cover Hurricane Damage? Here’s What Your Policy Actually Includes
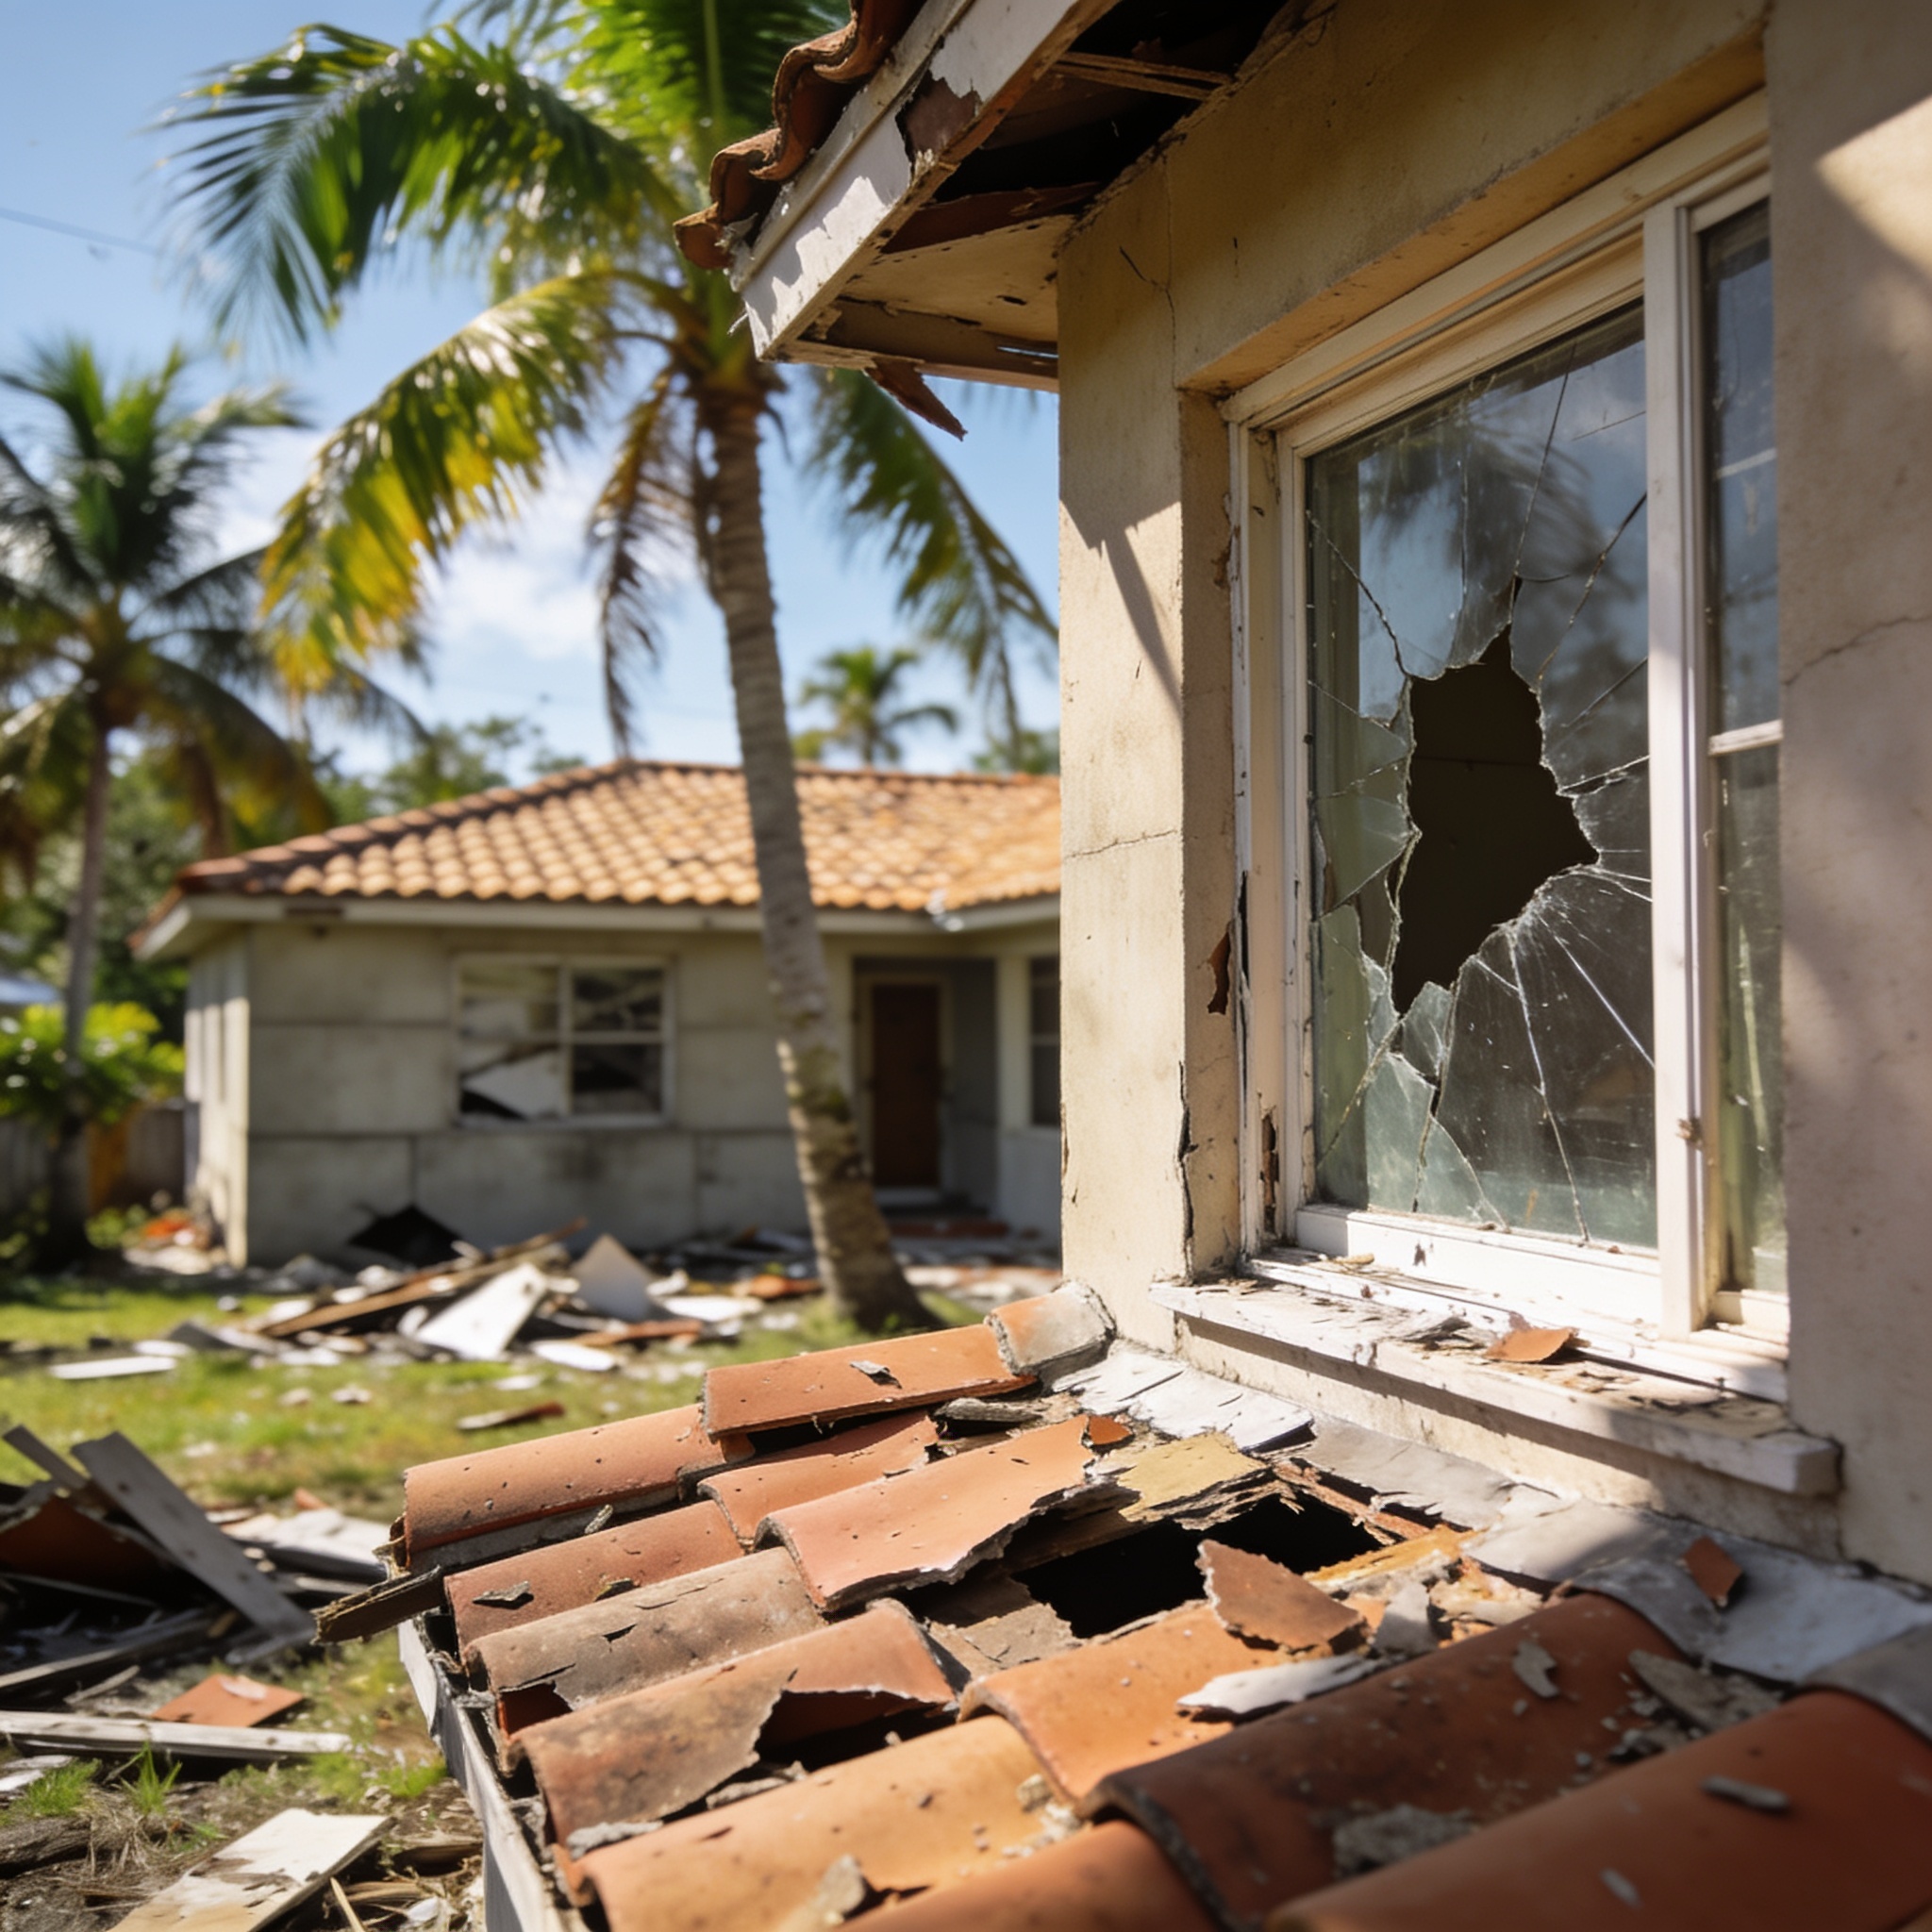
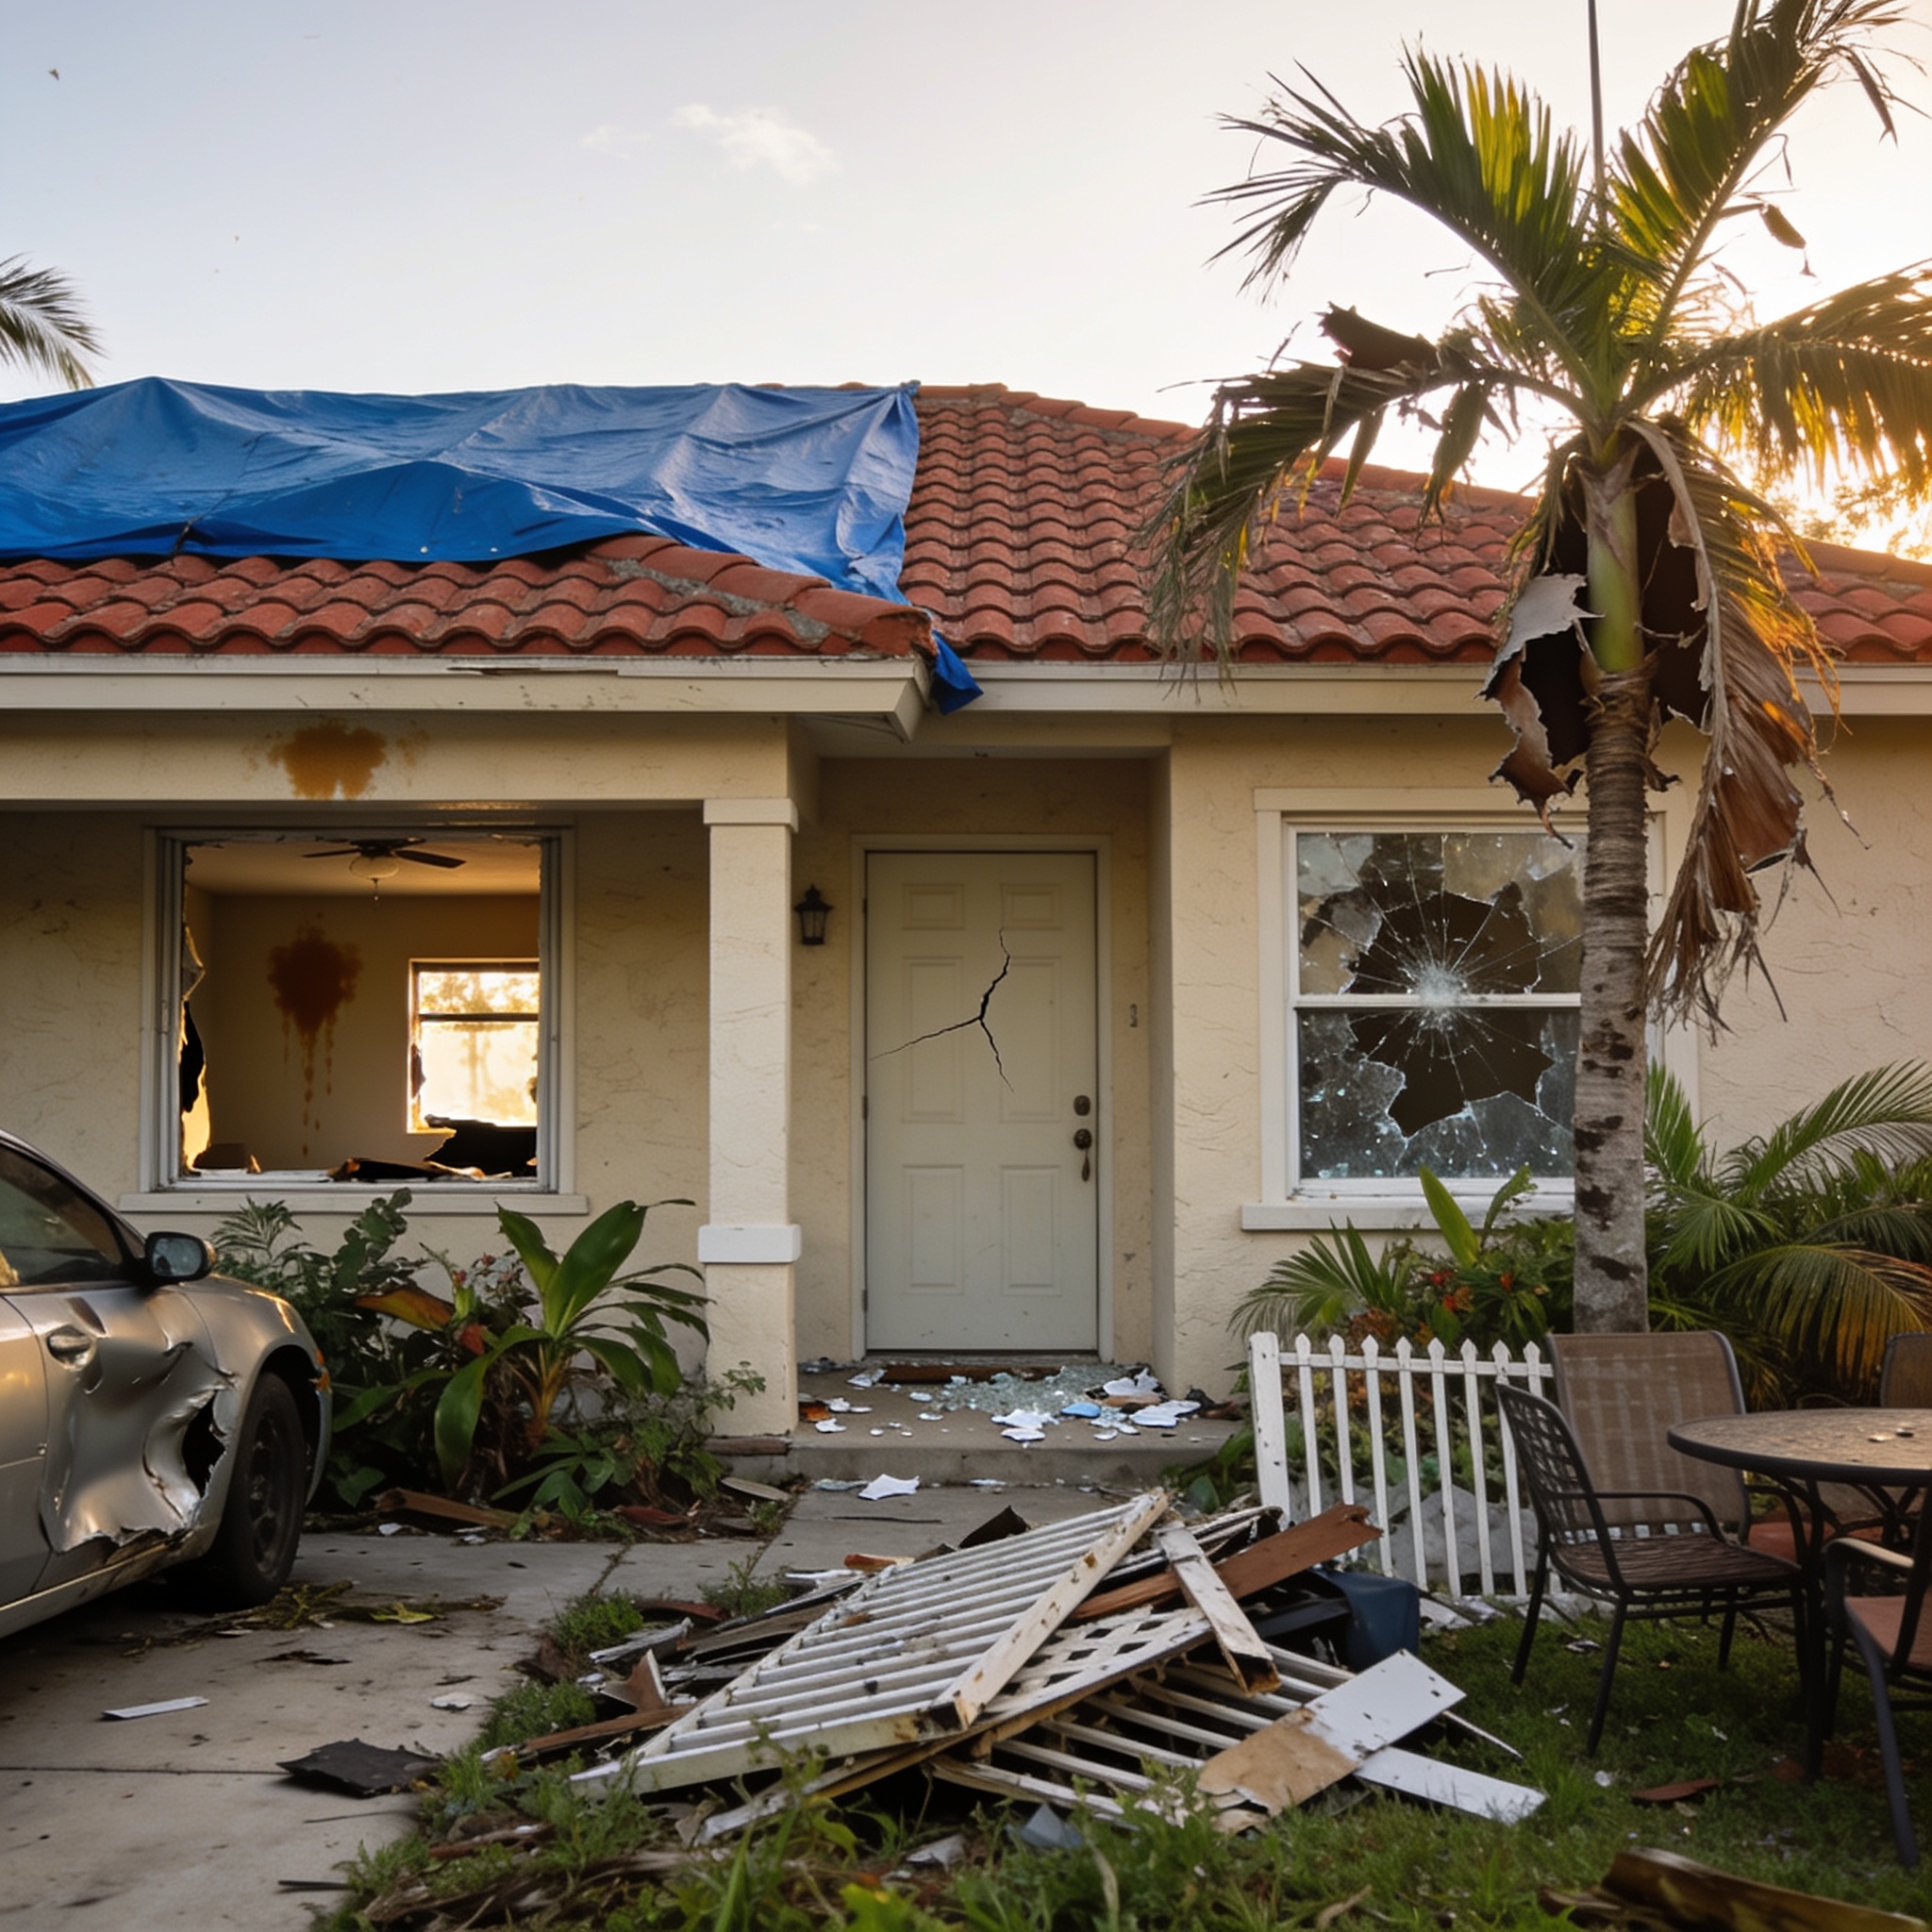
Renters insurance coverage to renters typically protects your personal belongings from wind damage and wind-driven rain. If a hurricane destroys your roof and rain ruins your furniture, your renters insurance policy usually provides the necessary coverage for damage to your belongings. This protection applies to the contents of your home, not the structure itself. The home insurance held by your landlord is designed to cover the building, while your renters insurance covers your personal property. Renters insurance can offer peace of mind by helping to cover the loss of your items after a storm.What Specific Types of Hurricane Damage Are Generally Not Covered by Renters Insurance?
Insurance companies generally exclude damage caused by rising water, storm surge, or external flooding from standard renters insurance policies. While your policy covers windstorm damage, it does not cover damage caused by the accumulation of water on the ground. If you experience water damage caused by a storm, you may need professional Water Damage Restoration to mitigate further loss. Always verify your specific declarations page to see what types of damage are excluded, as many policies specify what insurance does not cover regarding natural disasters.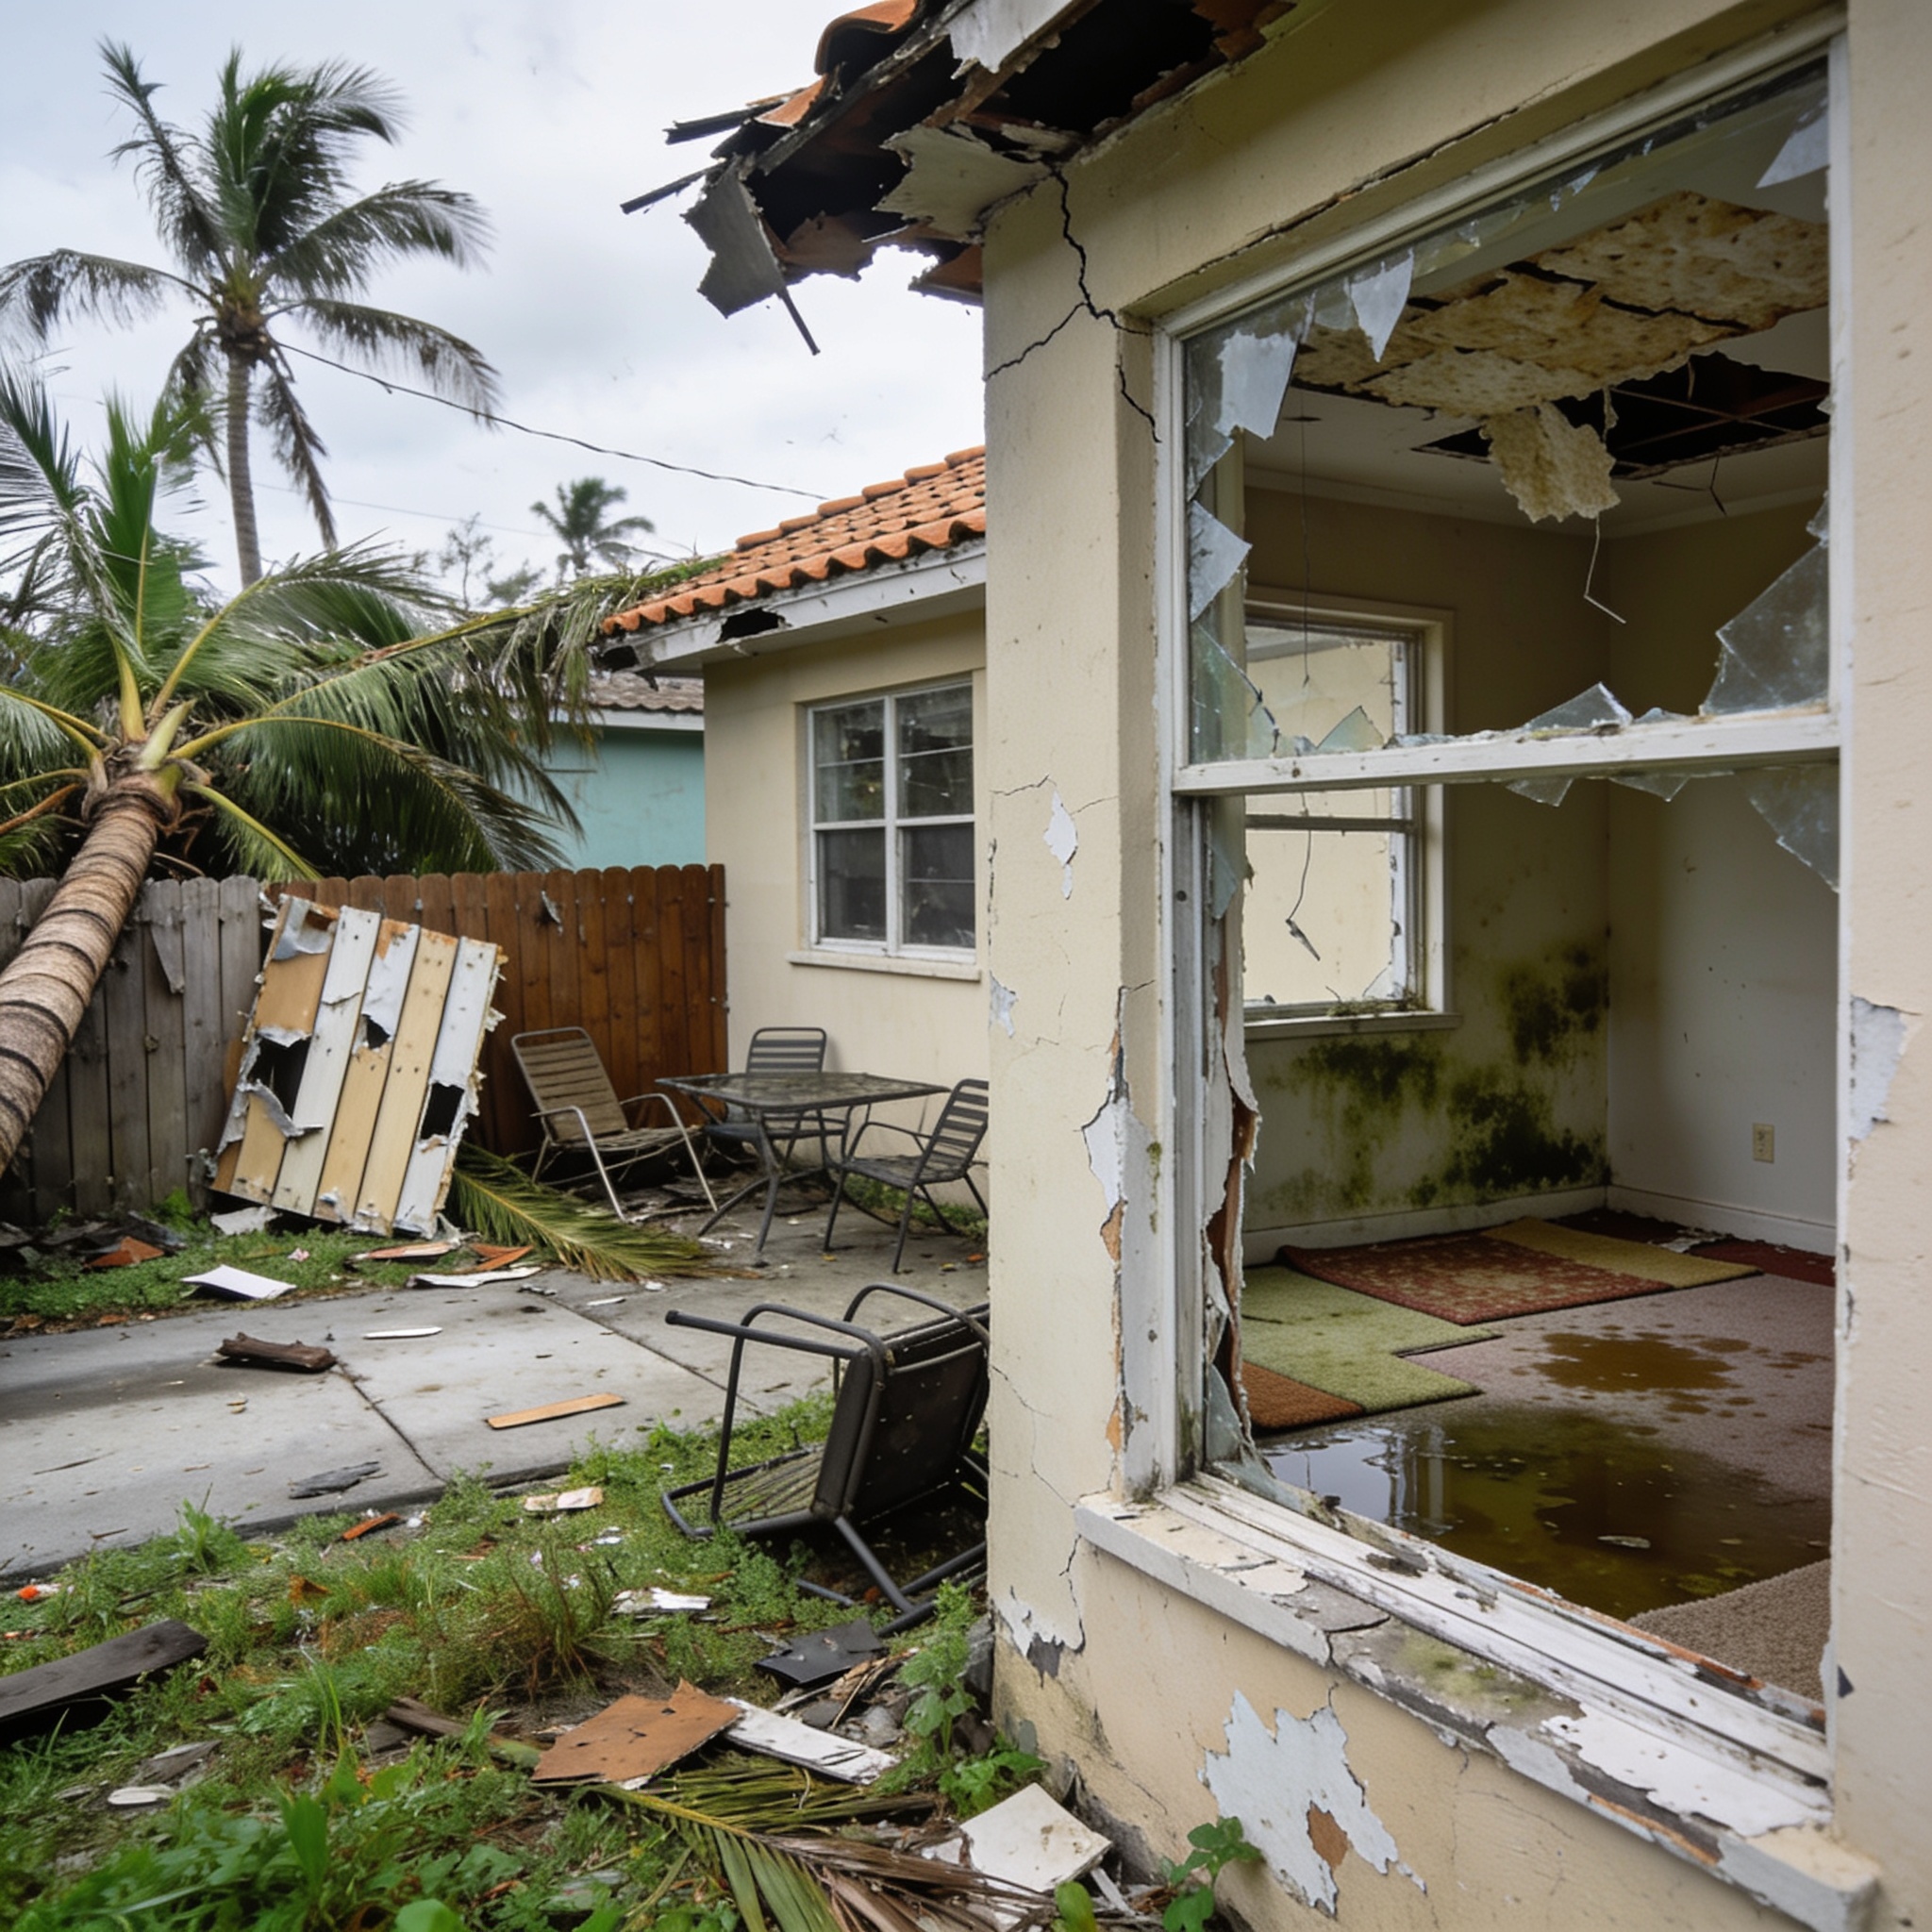
What Two Natural Disasters (Including Floods) Are Often Not Covered by Renters Insurance?
Standard renters insurance policies do not provide coverage for floods or earthquakes. You must purchase separate flood insurance policies and earthquake insurance to protect your belongings from these specific natural disaster events. Even in high-risk zones like Lee or Collier County, these perils are excluded from standard forms. Relying solely on a base policy leaves a significant gap in your financial security, especially regarding damage to the structure that may occur during a catastrophe. You should always consider flood insurance to fill these gaps.Does Renters Insurance Cover Flood Damage from a Hurricane?
Renters insurance does not cover flood damage caused by a hurricane, as flooding is defined as water rising from the ground. The National Flood Insurance Program provides specific flood coverage for renters who need to protect their belongings from rising water during a tropical cyclone. If your apartment is located in a low-lying area, you should consult with your state’s department of insurance about obtaining a contents-only flood policy. For immediate assistance after a storm, professional Water Damage Restoration can help assess the situation.Does Renters Insurance Cover Additional Living Expenses If My Rental Becomes Unlivable After a Hurricane?
Renters insurance may cover additional living expenses if your home is damaged by a covered peril, such as wind or fire. If a hurricane makes your apartment uninhabitable due to wind damage, your policy can pay for temporary housing and increased costs while you are displaced. This coverage is subject to your policy limits and the specific terms of your renters policy. Always keep receipts for all expenditures incurred during the displacement period.What Is a Hurricane Deductible for Renters Insurance and How Does It Work?
A hurricane deductible is a specific cost-sharing requirement that applies only to damage caused by a named hurricane. Unlike a standard flat-dollar deductible, a hurricane deductible is often calculated as a percentage of your total personal property coverage limit. For example, a 2% deductible on a $50,000 policy would require you to pay $1,000 out of pocket before the insurer pays for the remaining storm damage. This applies to damage to your personal belongings associated with a hurricane.Can I Get Renters Insurance Right Before a Hurricane Hits?
Most insurance providers will place a moratorium on new policies once a hurricane watch or warning is issued. You cannot purchase renters insurance to cover damage from a hurricane that is already in the forecast. Insurance companies require policies to be active well before a storm approaches to prevent adverse selection. Plan your coverage during the early months of the hurricane season to ensure you are protected against damage caused by hurricanes.What Coverage Options Should Renters Consider for Full Hurricane Protection?
Renters should consider a combination of a standard renters policy and a separate flood insurance policy for comprehensive protection. Combining these two types of insurance ensures that both wind-driven rain and ground-level flooding are addressed in the event of a storm. If you are unsure about your current coverage, review our is water damage covered by homeowners insurance to better understand your rights. This includes coverage for wind damage and protection against damage from hurricanes and severe weather events.How Much Does Renters Insurance Cost (Including High-Value Policies)?
The average cost for renters insurance in Florida ranges from $150 to $400 per year depending on your location and coverage limits. High-value policies that include scheduled personal property for expensive items like jewelry or electronics will increase your annual premium. Factors such as proximity to the coast and the age of the building also influence the final quote from your insurance agency. Ensure your renters insurance coverage is sufficient to replace your items in the event of hurricane-related damage.How Do I File a Renters Insurance Claim After a Hurricane?
Filing an insurance claim requires immediate action and thorough documentation of all property damage. You must document the damage with photos and videos before beginning any cleanup or hiring Water Damage Restoration professionals. Contact your insurance provider as soon as it is safe to do so to initiate the process. Keep a detailed inventory of all items lost to expedite the settlement, specifically noting damage renters insurance might cover regarding your personal property.Frequently asked questions
Here are the most common inquiries regarding how renters insurance interacts with hurricane-related events in Florida.Does my landlord’s insurance cover my furniture?
No, your landlord’s insurance only covers the physical structure of the building and their own liability. You are responsible for insuring your own personal belongings inside the unit.What if my power goes out and my food spoils?
Some policies include coverage for food spoilage caused by a power outage, but you must check your specific policy language. This is often subject to a small sub-limit or a deductible.Is wind-driven rain considered a flood?
Generally, no; wind-driven rain that enters through a hole in the roof or a broken window is considered wind damage. Flooding is defined as water that enters from the ground up.Can I get a discount for hurricane shutters?
Many insurance companies offer discounts for protective devices like hurricane shutters or reinforced windows. Ask your agent about potential credits for mitigation efforts.How long does an insurance claim take?
The timeline for an insurance claim varies based on the severity of the storm and the volume of claims in your area. Providing clear documentation and a detailed inventory will help speed up the process. SR
SWFL Restoration Editorial
Local restoration research team
Our editorial team verifies licensing and reviews for every restoration company in the directory and writes practical, Florida-specific guides to help homeowners act fast and protect their insurance claims after water, fire, mold or storm damage.